
Custody
What a proper vault audit looks like
A statement is a claim. An audit is evidence. Here is what a meaningful audit of your holdings should test — and how to ask for one.
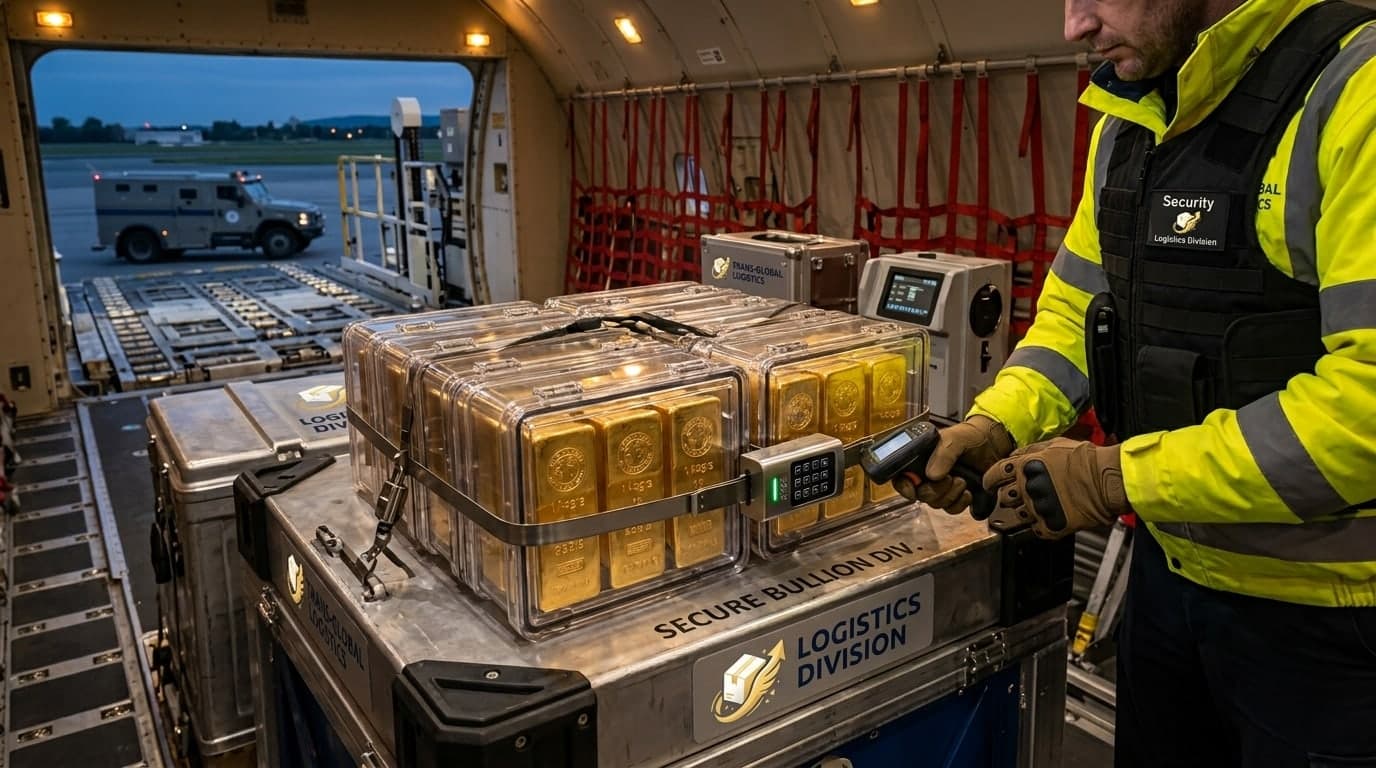
Your monthly statement tells you what your custodian believes you own. An audit tests whether that belief matches reality. For allocated bullion the test is concrete: every bar on your list should be on the shelf, with the right serial number, mark and weight.
Two kinds of count
A full count physically checks every bar against the records. It is thorough and time-consuming, so large vaults usually combine periodic full counts with more frequent sample counts, in which an auditor selects bars at random — including some the custodian did not expect to be chosen.
What the auditor should test
- Existence: is each bar on the list physically present?
- Identity: do the serial number, refiner mark, fineness and year stamped on the bar match the record?
- Weight: does a sample reweigh within tolerance of the recorded gross weight?
- Ownership: is each bar recorded against exactly one owner, with no bar appearing on two lists?
- Completeness: are there bars on the shelf that are not on any list?
The last test is the one most often skipped, and the one that catches the most interesting problems.
Independent and client audits
Custodians normally commission independent audits of their whole vault. Clients with significant holdings may also have the right — under their storage agreement — to inspect their own bars or appoint an auditor to do so. Our allocated storage agreement gives every client the right to an inspection at least once a year, on reasonable notice and accompanied by our staff.
Reconciliation between audits
We reconcile our records against the physical holdings at least twice a year, and every movement in or out of the vault is recorded against bar serial numbers in real time. Your portal shows the same bar list we use operationally — not a summary prepared for reporting.
How to ask
If you want to inspect your holding or appoint an auditor, message your account manager through the portal. We will agree a date, confirm who will attend, and prepare a bar-by-bar list for the visit.
Weighing and sampling
A count confirms that the right bars are present; it does not confirm that they are what they claim to be. Auditors therefore usually weigh a sample of bars against their recorded gross weight and inspect the stamps — refiner mark, serial number, fineness and year — for consistency. Weight differences within the tolerance of the scales are normal; anything outside it is investigated. For high-value holdings, a small number of bars may be tested non-destructively for authenticity, for example with ultrasound or electrical conductivity equipment.
What a clean report looks like
A good audit report is specific. It states the date of the count, who carried it out, the scope (full or sample), the method used to select any sample, and the result for each item tested. It lists any exceptions found and how they were resolved. Vague language — “holdings were reviewed and found to be in order” — tells you very little. If you receive a summary, ask whether the full report is available to you.
- Date and scope of the count.
- Names of the auditor and the custodian staff present.
- Sampling method and the bars selected.
- Exceptions found and their resolution.
Your own records
Keep your certificates and statements, and compare them occasionally. If the bar list on a new statement differs from the last one without a movement or transfer you instructed, ask why. Most differences have mundane explanations, but noticing them is how small errors are kept small.
This article is general information, not legal, tax or investment advice. Speak to a qualified adviser about your circumstances.
Keep reading
- Custody4 min read
Allocated or unallocated? What you actually own
Two accounts can show the same number of ounces and mean completely different things. Here is how to tell whether you own bars, or a promise.
Read more  Markets3 min read
LBMA Good Delivery, explained for owners
The 400-ounce bar is the currency of the wholesale gold market. Here is what the Good Delivery standard guarantees, what it doesn’t, and why it matters when you sell.
Read more Logistics3 min read
Anatomy of a chain of custody
Every hand-over is a moment where a bar could be swapped, lost or simply undocumented. Here is how a disciplined chain of custody closes each gap.
Read more